No Middleman, No Markup? FPSO Contracts Are Being Unbundled
As shipyards pursue broader EPC scopes and oil companies reconsider asset ownership and operating responsibility, the traditional bundling of FPSO construction, leasing and O&M is being reshaped.
In the past, an oil company developing a deepwater field would not normally go directly to a shipyard to order an FPSO. More often, it would award the project to a specialist FPSO contractor such as SBM Offshore, MODEC or Yinson. The contractor would arrange construction financing and asset ownership, lead engineering, procurement and project management, and select shipyards to build and integrate the hull and topsides. After start-up, it might also provide long-term leasing and operating services.
Under this contracting chain, the oil company dealt with the FPSO contractor, while the shipyard usually did the same. The yard performed much of the physical construction but rarely held the main FPSO contract with the oil company.
SBM and MODEC are not “middlemen” in the ordinary sense. What they sell is not a simple vessel but a floating production solution that combines project execution, asset arrangements and long-term operations. Oil companies have accepted this additional layer because someone must coordinate numerous contractors and equipment suppliers—and take responsibility for delivering the FPSO on schedule and keeping it operating reliably.
MODEC Is Taking Shipyard Competition Seriously
In July 2026, the MODEC Group Integrated Report 2025 stated: “In recent years, amid expanding FPSO demand, new players such as shipbuilders have sought entry into EPC projects.”
MODEC then explained that what distinguishes it from these new entrants is not only its FPSO construction record, but also the operating knowledge and data accumulated through long-term lease and O&M services. Its customer relationships allow it to become involved earlier, reserve shipyard capacity and long-lead equipment in advance, and help clients shorten time to first production.
The statement is especially notable coming from MODEC. The company owns neither factories nor shipyards and describes itself as a fabless company. Its core role is to select shipyards and contractors globally, organize engineering, procurement, construction, installation and commissioning, and serve as the main interface accountable to the oil company.
Some of the shipyards once selected and managed by MODEC are now moving one step forward and seeking EPC contracts directly from oil companies. On major international oil and gas developments, yards in South Korea, Singapore and China are increasingly competing alongside established EPC contractors for prime FLNG, FPSO and FPU contracts.
Direct FPSO procurement from shipyards is not new; Petrobras has long used similar arrangements. What has changed is the number of yards capable of assuming a broader engineering scope, while direct procurement and the unbundling of contract packages are appearing across more large projects.
P-84 and P-85 provide a clear example. In 2024, Petrobras, acting on behalf of the Atapu and Sépia consortiums, directly awarded Seatrium two newbuild FPSO contracts through an international tender. The contracts were worth approximately S$11 billion. Seatrium is responsible for engineering support, module fabrication, integration and commissioning, with delivery scheduled for 2029. Contracts of this kind show that shipyards with system-integration capabilities are no longer confined to subcontracted construction work.
Ownership, EPCI and O&M Are Being Recombined
The traditional FPSO lease model often linked asset ownership, project execution and long-term operations. The FPSO contractor invested capital, organized EPCI, held the asset and recovered its investment through lease and O&M contracts lasting 15, 20 or more years.
These functions no longer have to remain with the same company. An oil company can own the FPSO while assigning EPCI and O&M to specialists. It can take ownership during construction while retaining the original contractor for engineering or operations. Where its capabilities and project conditions allow, it can also procure a broader delivery scope directly from a shipyard.
The four commercial models listed in SBM Offshore’s 2025 annual report—Lease and Operate, Build-Operate-Transfer, Sale and Operate, and Direct Sale—reflect this shift. Clients may buy a long-term service that includes the asset and its operation, or fund and own the FPSO themselves while purchasing only project execution or operating services.
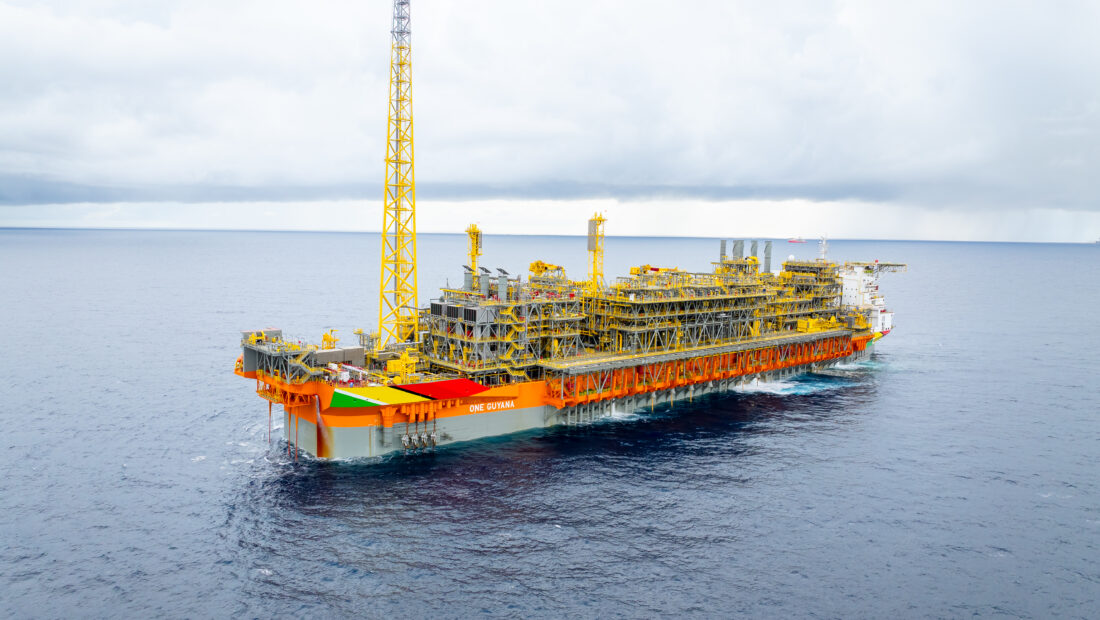
ONE GUYANA offers another form of unbundling. In February 2026, ExxonMobil Guyana purchased the FPSO early for approximately $2.32 billion and took ownership, while SBM will continue to operate and maintain it until 2035. In May of the same year, SBM received contracts from Petrobras for SEAP-I and SEAP-II. The Petrobras-led consortiums will own both FPSOs, while SBM will design and build them and provide an initial 6.5 years of operations and maintenance under separate O&M contracts. These cases do not simply remove SBM; they reallocate asset ownership, project delivery and long-term operations.
This does not mean direct procurement will replace the lease model. Development timelines, financing arrangements, schedule requirements and operator capabilities differ from one field to another, so the appropriate FPSO model will also vary. The real change is that oil companies are no longer limited to one option: work previously bundled into a single long-term contract can now be recombined to fit each project.
As the FPSO market has strengthened, specialist contractors have accumulated more orders, while execution resources—including high-quality yard slots, engineering personnel and long-lead equipment—have tightened. At the same time, some oil companies have the financial capacity to own the assets, and shipyards are improving their engineering, procurement and project-management capabilities. Together, these factors make contract unbundling and direct procurement more feasible.
Specialist FPSO Contractors Face Pressure from Both Sides
This is where the competitive pressure on MODEC and SBM becomes most visible.
On the client side, some oil companies are beginning to own FPSOs themselves and arrange project execution, asset ownership and long-term operations separately. What they take back first is often control of the asset and the contracts—not necessarily engineering and operations at the same time—but the FPSO contractor’s traditional long-term lease revenue is reduced.
On the supply-chain side, shipyards that once concentrated on hulls, modules and integration are moving into engineering, procurement, system integration and commissioning. When a yard wins the prime EPCIC contract, it captures not only more construction revenue but also part of the project-orchestration role previously held by MODEC and SBM.
Oil companies are extending down the chain while shipyards move up it. Asset returns, engineering revenue and long-term service income that were once concentrated with specialist FPSO contractors are being divided from both directions.
MODEC and SBM are not standing still. SBM allows clients to take ownership during construction while retaining project-execution and coordination capabilities through standardized designs and the Fast4Ward platform. MODEC places greater emphasis on early engagement, global supply-chain coordination and O&M data, seeking to preserve EPCI or operating work even when it will not own the FPSO over the long term.
If One Layer Disappears, Where Does the Risk Go?
When an oil company contracts directly with a shipyard, one contractual layer may appear to disappear. The work previously performed by MODEC and SBM does not.
If the oil company owns the FPSO, it takes on more capital exposure and long-term asset risk. If the shipyard assumes a full EPCIC scope, it becomes responsible for cost, schedule, system integration, installation, commissioning and performance. If project execution and O&M are awarded to different companies, the oil company must also manage the interface between construction and long-term operations.
The more a contract is split, the easier it becomes to price each package separately—but coordination responsibilities between packages also increase. An oil company may save part of the long-term lease cost while taking on more project-management and interface risk. A shipyard may win a larger scope, but it must also develop the engineering and risk-management capabilities previously provided by the FPSO contractor.
This is why MODEC stresses operating experience in its report. A shipyard can prove that it can build an FPSO. MODEC must prove that knowledge gained from long-term O&M can improve design, equipment selection and maintenance planning—bringing the FPSO on stream sooner and keeping it reliable over the next two decades.
“No middleman, no markup” is therefore not a complete explanation of this shift. Oil companies no longer accept only one form of packaging, and shipyards are competing for more work. Yet someone must still connect design, supply chain, construction, commissioning and operations—and remain accountable for the final result.
The central question facing MODEC and SBM is not whether system integration has value, but whether they can continue to occupy that position by default. Oil companies can now choose again: manage the interfaces themselves, ask a shipyard to deliver the complete scope, or continue assigning primary responsibility to a specialist FPSO contractor.
No business model is permanent, and no industry’s division of roles is settled forever. A capability that once made a company indispensable will not necessarily be needed in the same form indefinitely. What protects a company’s position is not repeatedly proving what it got right in the past, but still being able to answer the most practical question after customers, technology and industrial roles have changed: why are you still needed today? The same is true of people.