Is a New Dawn Emerging for the Offshore Rig Market?
Higher dayrates, reactivated assets and selective newbuild plans point to a recovery, but continued recycling shows that contracts, asset condition and regional demand still divide winners from stranded rigs.
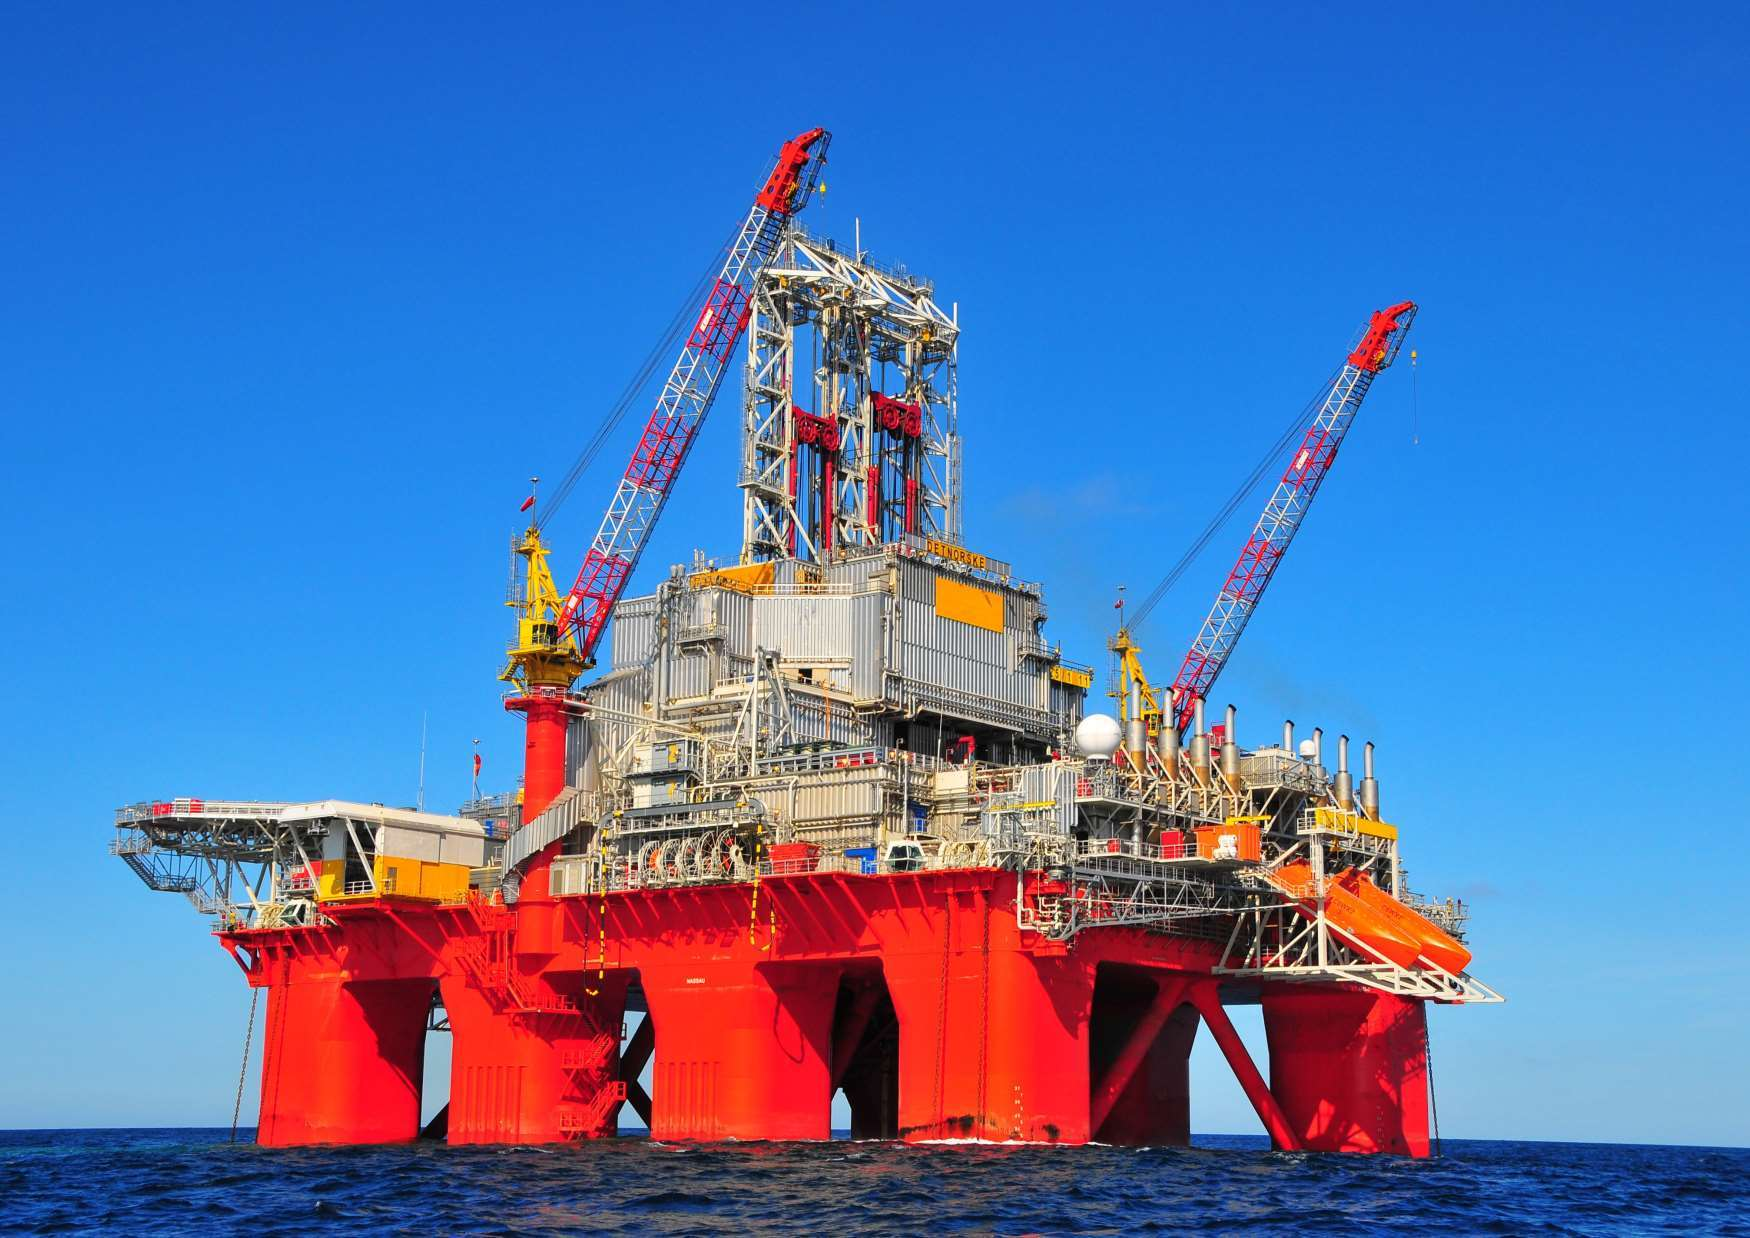
The offshore rig market has sent a seemingly contradictory set of signals in 2026. China Oilfield Services Limited is advancing early-stage work on four jack-ups and two deepwater semisubmersibles, while CNPC Offshore Engineering is buying two 400-ft jack-ups. Overseas, some unfinished rigs are returning to construction and some idle units have secured new work, yet other rigs—including one delivered as recently as 2011—are being sold for recycling.
The market is recovering, but not every rig, basin or shipyard is recovering at the same pace. This is better understood as a structural recovery. Demand is lifting dayrates and utilisation for selected high-specification assets while creating completion, reactivation and upgrade work for existing units. A broad newbuild cycle, however, will still depend on long-term contracts, construction costs and investment returns.
Chinese operators are adding drilling capacity
COSL’s board approved a feasibility study for four high-performance jack-up rigs in June and a second study for two new-generation deepwater moored semisubmersibles in August. Procurement for basic-design services has begun for the four jack-ups, which are intended mainly for Bohai operations. All six units nevertheless remain at the feasibility and design-preparation stage; they should not yet be described as rigs under construction.
CNPC Offshore Engineering has chosen a faster route to fleet expansion. A procurement result announced in late September named Dalian Shipbuilding Offshore Co as the supplier of two 400-ft jack-ups at a quoted price of RMB1.7722 billion. The requirement is intended to support offshore work including Bohai and Suriname, with the two rigs scheduled for delivery by December 2026 and the end of May 2027 respectively.
The Dalian yard has already used existing inventory to complete a similar transaction. In 2023, COSL agreed to buy four JU2000E jack-ups from the company. The first, Hai Yang Shi You 945, was delivered one month after the sales agreement, with the remaining three subsequently joining COSL’s fleet. For a buyer, acquiring a sound existing asset can be faster than a clean-sheet newbuild. For a yard, it can provide a route to monetise legacy inventory and restore cash flow.
Legacy rigs are finding new routes to market
The previous offshore downturn left a substantial population of unfinished or long-idle rigs. As demand improves, the central question is not simply whether those assets can be sold, but whether completing and returning them to service still makes economic sense.
In October, RigCo and Seatrium announced plans to advance four unfinished rigs with an estimated total project value exceeding S$500 million. The seventh-generation drillship Can Do and harsh-environment jack-up Jasper are targeted for delivery in 2027 and 2028 respectively, while plans for two harsh-environment mid-water semisubmersibles remain under assessment. These units are legacy Keppel assets. Completion alone will not put them to work; charters or other monetisation arrangements will still be required.
CIMC’s Beacon Pacific has progressed further. Serica Energy plans to deploy the semisubmersible from the third quarter of 2027 under a firm six-well programme with further options. Partial reactivation has started, and Odfjell Drilling will manage mobilisation, transit to the United Kingdom and operations during the contract.
Such programmes reflect demand from infill drilling, enhanced recovery and eventual plug-and-abandonment work in mature basins. Even after a contract is signed, however, a rig must complete inspections, maintenance, crewing, mobilisation and customer acceptance. The interval between award and first well can therefore be substantial.
Dayrates are rising, but demand is uneven
In its third-quarter 2026 materials, Noble said leading-edge dayrates for Tier 1 drillships were in the US$450,000–US$500,000 range, while ultra-harsh-environment jack-ups were earning roughly US$230,000–US$300,000. Selected high-specification rigs are also securing multi-year work. Transocean disclosed in April that Transocean Barents had won a fixed term of approximately 1,095 days in Norway at US$450,000 per day. If all options are exercised, the programme could continue into 2034.
High headline rates do not mean every rig has enough work. Noble reported 70% utilisation across its 28 marketed rigs in the third quarter. Its five marketed ultra-harsh-environment jack-ups achieved 86% utilisation, while 66% of its 23 marketed floaters were contracted. The figures cover one contractor, but they illustrate the divergence between asset classes.
Westwood expects committed drillship utilisation to reach 95% by the end of 2026, up from 92% in 2025, while jack-ups are forecast to ease from 91% to 88%. “Committed utilisation” includes future work already under contract or commitment; it does not mean that every unit is currently operating. The jack-up outlook also remains sensitive to project timing in major markets such as the Middle East.
Water depth, metocean conditions, well design and customer requirements limit interchangeability. Even rigs with similar headline specifications can face very different commercial prospects depending on their location, maintenance condition, mobilisation distance, class status and customer acceptance record.
Why some rigs return while others are recycled
VALARIS MS-1, the semisubmersible Valaris sold for recycling in September, was built by Jurong in Singapore and delivered in 2011. With a maximum designed operating water depth of about 8,200 ft, it was not among the oldest rigs in the fleet. Valaris did not disclose the specific economics behind the decision, but the case shows why age alone does not determine commercial value.
A long-idle rig may require equipment restoration, class surveys, recertification, recruitment and training, mobilisation and customer-specific upgrades before it can work again. Noble’s investor materials put the market-entry cost for some cold-stacked or shipyard-held seventh-generation drillships at roughly US$100 million–US$300 million. That is a complete market-entry estimate, not a quoted price for one reactivation job.
Idle capacity on paper does not necessarily mean a suitable rig is available when an operator needs it. If expected contract income cannot cover restoration cost, lead time and subsequent operating risk, recycling can be more rational than continued ownership.
Why higher dayrates have not triggered a newbuild wave
At US$450,000 per day and 300 working days a year, a drillship would generate gross annual revenue of about US$135 million. That is not profit. Crewing, maintenance, insurance, shore support and mobilisation must be paid, alongside debt service, equipment upgrades and the cost of idle gaps between contracts. Looking only at dayrates can therefore overstate a newbuild’s return.
Delivery timing matters just as much. A new rig can take years to build, while operators may be unwilling to lock in drilling plans that far ahead. Rig owners and lenders will not commit capital on short-term rates alone. Saudi Arabia illustrates how sustained construction depends on long-duration demand: Saudi Aramco disclosed a commitment to lease 20 offshore rigs from ARO Drilling over a ten-year period beginning in 2023. IMI and ARO have continued the KINGDOM jack-up programme and identify development of the local supply chain as a core objective.
Without long-term backlog, buying, completing or reactivating an existing rig may require less capital and deliver capacity sooner. That route has limits. Poor condition, upgrade cost, mobilisation distance and local rules can erase an apparent purchase discount. COSL’s planned jack-ups are intended for Bohai conditions; a lower-priced idle unit elsewhere may not satisfy the area’s well and operating requirements.
Newbuild proposals tailored to specific demand are beginning to appear. A larger order cycle will require more stable, longer-duration work so that owners and lenders can see a credible path to recovering their investment.
Where the opportunities lie for Chinese companies
More rig investment creates work for yards and equipment suppliers, but a rig’s contract value is not the yard’s profit. Drilling packages, well-control equipment, dynamic positioning, power and control systems bring specialist suppliers into the project, while subcontracting, financing, bonds and project management consume part of the headline value.
For Chinese yards with rig-building experience, completion and reactivation work may arrive before clean-sheet newbuilds. Yet hidden scope is usually harder to estimate. Problems discovered only after equipment is opened up can change both cost and schedule. Establishing asset condition before pricing—and defining responsibility for additional work and change orders—is central to protecting margins.
Reactivation also depends on original equipment manufacturers for spares, software and inspection support. A yard that can organise those resources and complete system integration, testing and delivery is selling more than steelwork; it is providing a broader technical-integration service.
Equipment suppliers must address compatibility and lifecycle support. Can a replacement connect to the existing control system? Will it satisfy class and local operating requirements? Who will provide field support after a failure? Technical documentation, commissioning capability, spares networks and long-term maintenance plans can matter more than a one-off price.
International projects also bring localisation requirements. KINGDOM 4 is being built in Saudi Arabia with an explicit focus on the local supply chain. Chinese participation may therefore involve design, equipment, modules, commissioning and after-sales service rather than complete rig assembly. Local operating capability is equally important for Chinese asset owners: CIMC owns Beacon Pacific, while Odfjell Drilling will manage the rig during its UK contract, combining asset capability with regional operating experience.
For many Chinese suppliers, the first order from this recovery may be a package of spares, an equipment inspection or a control-system upgrade. The more valuable question is whether that initial scope can become an entry point to long-term rig maintenance, modernisation and operational support.
The offshore rig market is seeing a new dawn, but the first assets in the light are high-specification units in good condition that can enter a specific market quickly, together with newbuild programmes backed by long-duration demand. The recovery is real, but it is not universal. The opportunity lies in judging asset condition, contract quality, regional demand and lifecycle cost with precision.